

An employer match is when your organization contributes to an employee’s retirement plan, usually by matching a portion of what they save themselves. Think of it as a bonus paid on top of their regular salary, designed to reward your team for their long-term financial planning. It’s one of the most direct ways to boost an employee’s retirement savings.
The Employer Match Is A Powerful Retention Tool
For nonprofit leaders, an employer match is far more than just another line item in the budget. It’s a powerful strategic tool for attracting and, more importantly, retaining dedicated, mission-driven talent in an incredibly competitive environment.
When you offer a match in a 401(k) or 403(b) plan, you’re making a direct investment in your team’s future. It rewards them for their commitment to both their own financial health and the organization's mission.
Competing Beyond Salary
Nonprofits often struggle to compete with for-profit sector salaries. A well-structured employer match helps level the playing field, showing a deep commitment to your team's overall well-being. It sends a clear message that you value their contributions and are invested in their long-term security.
This benefit shifts the compensation conversation from just take-home pay to a more complete picture of total rewards. It becomes a tangible symbol of a supportive and caring workplace culture, which can be a deciding factor for top candidates.
An employer match transforms retirement saving from a solo effort into a partnership. It shows employees that their organization is actively helping them build a secure future, which fosters significant loyalty and goodwill.
A Foundation for Financial Wellness
A matching program also drives much higher participation rates in your retirement plan. When employees see their savings instantly amplified by the organization's contribution, they are far more motivated to start saving earlier and contribute more consistently. This not only benefits the individual but also strengthens the overall financial wellness of your entire workforce.
A strong benefits package, with the employer match as its cornerstone, leads to some powerful outcomes:
- Improved Employee Morale: Staff feel valued and supported, knowing their employer is helping them prepare for retirement.
- Reduced Financial Stress: Providing concrete tools for long-term security can alleviate a major source of anxiety for employees.
- Enhanced Recruitment: A competitive match is a standout feature that makes your organization more attractive to skilled professionals.
Ultimately, designing a thoughtful employer match program is an act of responsible stewardship. It aligns your budget with your values while fulfilling your fiduciary responsibilities. You can learn more by exploring different types of nonprofit retirement plans to find the best fit for your team.
Choosing The Right Contribution Strategy For Your Nonprofit
Figuring out the right contribution strategy is the first real step toward building a retirement plan that actually works for your nonprofit's mission and budget. Crafting a smart employer match 401k strategy means finding that sweet spot between predictability, flexibility, and getting your employees excited to save.
The choice you make will ripple through your budget, your administrative workload, and how your team sees this important benefit. Let's break down the most common approaches in practical terms to help you find the best fit.
The Predictability Of A Fixed Match
A fixed match is one of the most straightforward and popular ways to go, especially for nonprofits. In this model, your organization commits to matching employee contributions up to a set percentage of their salary, using a clear, unchanging formula.
For instance, you might decide to match 100% of what an employee saves, up to 3% of their pay. This clarity makes it incredibly easy for your team to understand exactly what they need to do to get the full benefit. It also gives your finance team excellent budget predictability since you can forecast the maximum potential cost based on total payroll.
The Flexibility Of A Discretionary Match
For organizations where funding or revenue can swing from one year to the next, a discretionary match offers some much-needed breathing room. Instead of being locked into a fixed formula, your board can decide each year whether to offer a match and how generous to be.
This approach lets you reward your team in strong financial years while protecting your budget during leaner times. The trade-off, however, is a lack of predictability for your staff, which can make it harder for them to plan their own savings.
A key to success with a discretionary match is clear and timely communication. When a match is announced, it's often seen as a bonus that celebrates a successful year, reinforcing a shared sense of accomplishment.
The Simplicity Of A Safe Harbor Match
Many nonprofits are drawn to a Safe Harbor match because it massively simplifies compliance and administration. By adopting a specific, generous matching formula—like a 100% match on the first 3% of employee contributions plus a 50% match on the next 2%—your plan can automatically pass certain annual IRS nondiscrimination tests.
This structure is a powerful way to ensure your plan benefits everyone equitably, not just your highest earners. Opting for a Safe Harbor match cuts down on administrative headaches and minimizes the risk of compliance failures, freeing up your team to focus on your mission. Choosing the right plan is a big decision, and you can explore more about how to choose a retirement plan that fits your nonprofit's unique needs.
Understanding Nonelective Contributions
It's also important to get your head around nonelective contributions, which are fundamentally different from a match. With this strategy, your nonprofit contributes to every eligible employee’s retirement account, whether they contribute a single penny themselves.
For example, you might decide to contribute 3% of every eligible employee’s salary to their 401(k) or 403(b). This approach guarantees that every single person on your team benefits from the retirement plan, which can be a powerful statement about your commitment to their long-term financial well-being.
While all sorts of matching formulas exist, a few are more common than others. The most prevalent 401(k) matching formula out there is 50% on the first 6% of pay. For someone earning $100,000, contributing 6% ($6,000) would bring in a $3,000 employer match—valuable "free money" that can seriously accelerate their savings. You can see more insights on average 401(k) match structures on Kiplinger.com.
Each strategy brings something different to the table. Let’s lay them out side-by-side to make the decision clearer.
Comparing Employer Contribution Strategies For Nonprofits
Each contribution type offers different advantages, helping nonprofit leaders assess which approach best fits their budget, administrative capacity, and employee engagement goals.
Fixed Match
- How It Works: A set formula (e.g., 100% on the first 3%) that doesn't change year-to-year.
- Key Benefit for Nonprofits: High budget predictability and easy for employees to understand.
- Primary Consideration: A fixed financial commitment, even in tighter budget years.
Discretionary Match
- How It Works: The board decides each year whether to contribute and how much.
- Key Benefit for Nonprofits: Maximum budget flexibility; can be used as a reward in good years.
- Primary Consideration: Lack of predictability for employees can hinder their savings planning.
Safe Harbor Match
- How It Works: A specific, generous formula that helps the plan automatically pass IRS tests.
- Key Benefit for Nonprofits: Simplifies compliance and reduces administrative burden and legal risk.
- Primary Consideration: The required contribution is generous and may be more costly than other options.
Nonelective Contribution
- How It Works: A contribution made to all eligible employees, regardless of whether they save.
- Key Benefit for Nonprofits: Guarantees every employee benefits, boosting morale and financial wellness.
- Primary Consideration: Cost is based on total payroll and is not tied to employee participation.
Ultimately, your choice will come down to your organization's financial stability, administrative capacity, and your goals for employee engagement.
How To Accurately Forecast Your Budget Impact
Putting an employer match into action means moving from a great idea to a solid financial plan. For nonprofit finance leaders, the most critical step is figuring out the true cost. This process takes the mystery out of budgeting and gives your leadership team the confidence to make data-driven decisions that balance generosity with fiscal responsibility.
Forecasting isn't guesswork; it's about modeling different scenarios. By using a sample roster of your own employees, you can project the financial impact of various matching formulas and see what happens at different participation rates. You might be surprised to find that a meaningful match is often more affordable than you think.
Starting With Your Payroll Data
The first step is to pull together some essential data for every eligible employee. You don’t need fancy software to get this done. A simple spreadsheet is all it takes to build a powerful forecasting tool.
For each employee, you'll want to list their:
- Annual Salary: This is the foundation for calculating both employee contributions and your potential match.
- Age: While not used directly in the match calculation, age helps you understand your workforce demographics.
- Estimated Contribution Rate: This is the percentage of their own salary they are likely to contribute.
You can create different columns to model various participation scenarios, like low (25% of employees participate), average (50%), and high (75%). This will give you a realistic range of potential costs instead of a single, rigid number.
Modeling Different Matching Formulas
With your employee data organized, you can now plug in different matching formulas to see how they affect your budget. Let’s walk through a practical example to see how this works for a hypothetical nonprofit.
Imagine an employee earning $60,000 per year. Here’s how three common matching structures would impact your budget for that one person, assuming they contribute enough to get the full match:
Dollar-for-Dollar Match (Up to 3%): Your organization matches 100% of the employee's contribution up to 3% of their salary. The maximum annual cost to you would be $1,800 ($60,000 x 3%).
Partial Match (50% on the first 6%): Your organization matches 50 cents for every dollar the employee contributes, up to 6% of their salary. The maximum annual cost here is also $1,800 (($60,000 x 6%) x 50%).
Safe Harbor Match (100% on 3% + 50% on next 2%): This is a popular formula that helps simplify compliance testing. The maximum cost would be $2,400 (($60,000 x 3%) + ($60,000 x 2% x 50%)).
By running these formulas across your entire employee roster and factoring in different participation rates, you create a clear budget forecast. This process turns abstract ideas into concrete numbers your board can understand and get behind. As you plan, you can find more guidance on how to reduce retirement plan administration costs without reducing benefits to further stretch your budget.
This flowchart shows how common employer contribution strategies flow from predictable to more flexible options.
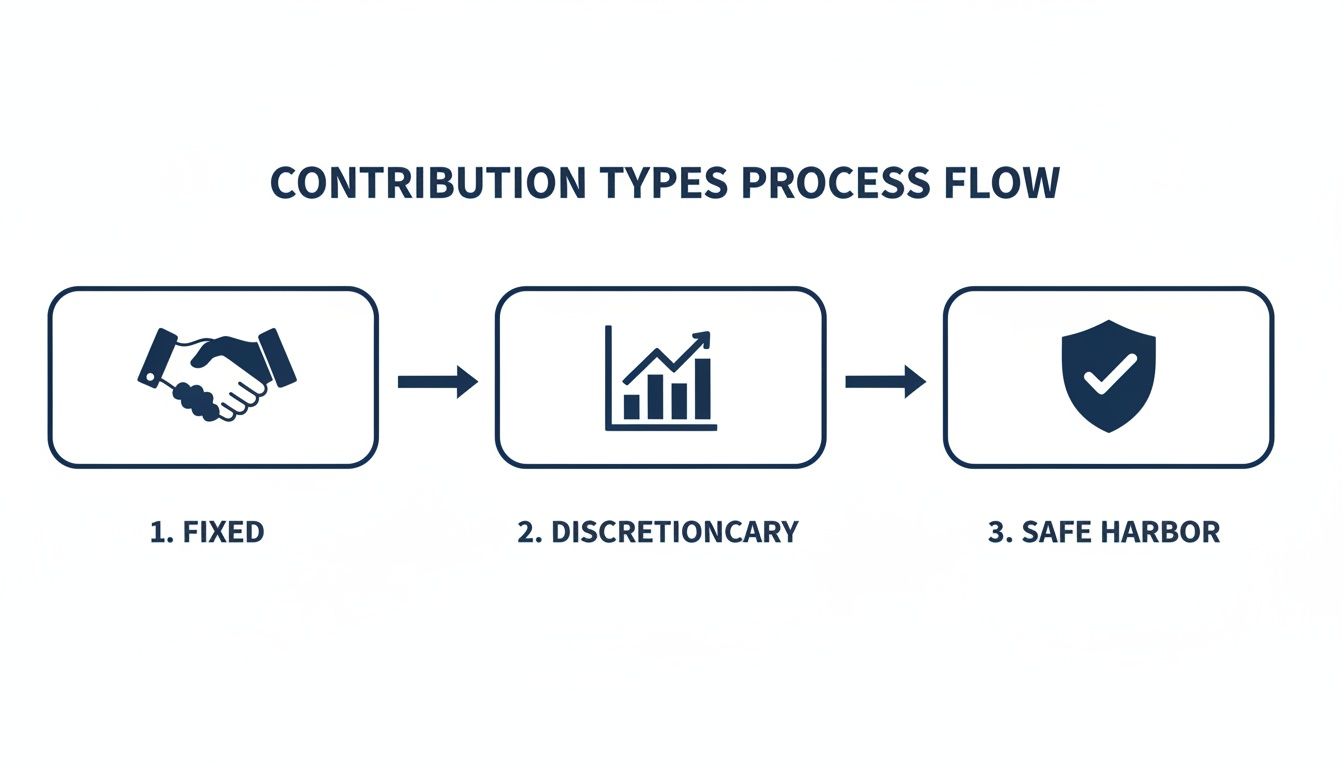
The visualization highlights that while Fixed and Safe Harbor matches offer more budgeting certainty, a Discretionary match gives you financial flexibility from year to year.
Factoring In IRS Contribution Limits
As you design your plan, it’s essential to keep regulatory guidelines in mind. The IRS sets annual limits on the total amount that can be contributed to a retirement account, which includes both employee and employer contributions. For 2024, the total combined contributions cannot go over $69,000 or 100% of the employee's compensation, whichever is less.
It’s crucial to remember that your employer match contributions count toward this overall limit. While most nonprofit employees won't come close to this cap, being aware of it is a key part of responsible plan management and fulfilling your fiduciary duty.
This limit ensures that retirement plans are used for their intended purpose—helping people save for the future—and not as improper tax shelters. Keeping these rules in view helps ensure your plan stays compliant.
The average 401(k) employer match is typically between 4% to 6% of an employee's compensation, a benchmark that has held steady since 2020. This means for an employee earning $100,000, a common employer contribution might be $4,000 to $6,000, but only if the employee contributes enough to earn it.
Designing Vesting Schedules To Encourage Loyalty
An employer match is a major commitment from your nonprofit, but its real power to inspire loyalty comes alive when you pair it with a smart vesting schedule. Vesting is simply the timeline an employee follows to gain full ownership of the matching funds you contribute to their retirement plan. Think of it as earning the match over time.
While an employee’s own contributions are always 100% theirs from day one, your matching funds can be tied to their length of service. This structure rewards long-term commitment and helps protect your organization’s investment if an employee leaves after just a short time. The right schedule reinforces a culture of appreciation and supports organizational stability.
A well-designed vesting schedule is a powerful retention tool. It creates a clear incentive for talented staff to stick around, knowing their loyalty translates directly into a more secure financial future. When your goals and your employees' goals are aligned like this, you've got the foundation of a successful benefits strategy.
The Two Main Types Of Vesting Schedules
When it comes to structuring your vesting plan, there are two primary models most nonprofits consider. Each one takes a different approach to rewarding tenure, and the best choice really depends on your specific retention goals and organizational culture.
Figuring out these options is the first step in creating an employer match 401k plan that not only attracts great people but keeps them dedicated to your mission for years to come.
Cliff Vesting: This is an all-or-nothing approach. With a cliff schedule, an employee becomes 100% vested in all employer contributions on a specific date—but they are 0% vested right up until that day. For example, on a three-year cliff schedule, an employee who leaves before their third anniversary forfeits all matching funds. The day they hit that three-year mark, they gain full ownership. It’s a powerful way to encourage staff to reach a key service milestone.
Graded Vesting: This model offers a more gradual path to full ownership. An employee’s ownership stake increases step-by-step over several years. A common six-year graded schedule might grant 20% ownership after two years of service, then another 20% each year after that until the employee is fully vested after six years. This approach rewards employees progressively for their continued service.
Vesting schedules aren't about penalizing employees who leave; they're about rewarding those who stay. They transform the employer match from a simple contribution into a tangible acknowledgment of an employee's ongoing dedication to your cause.
Choosing The Right Schedule For Your Nonprofit
The decision between cliff and graded vesting comes down to your strategic goals. If your main goal is to keep staff through a critical initial period—say, the first two or three years—a cliff schedule can be incredibly effective. It sets a clear, powerful incentive to stay with the organization through that window.
On the other hand, if you want to reward ongoing loyalty year after year, a graded schedule is probably a better fit. It gives employees a sense of continuous progress and acknowledges their commitment at each step of their journey. Watching their ownership stake grow annually can be really motivating and helps foster a sustained connection to your mission.
Staying Compliant With Nondiscrimination Testing
For any nonprofit leader acting as a fiduciary for your retirement plan, compliance isn't just a goal—it's a legal duty. One of the trickiest areas to navigate is nondiscrimination testing (NDT). These are annual tests required by the IRS to make sure your plan benefits everyone on your team equitably, not just your leadership or other highly compensated employees (HCEs).
Think of it as a fairness check. The IRS wants to see that your plan doesn't end up being a tax shelter for the highest earners while leaving everyone else behind. Understanding how these tests work is critical before you even think about designing an employer match 401k program.
The Key Nondiscrimination Tests Explained
While the names sound technical, the two main tests for 401(k) and 403(b) plans are actually pretty straightforward.
- The ADP Test: This test looks at the Actual Deferral Percentage. It compares the average percentage of salary that HCEs contribute to the plan against the average percentage from all other employees, known as non-highly compensated employees (NHCEs).
- The ACP Test: This test focuses on the Actual Contribution Percentage. It does the same comparison but looks at employer matching funds and any after-tax employee contributions.
If the gap between what your HCEs save and what your NHCEs save is too wide, the plan fails. Failing can be a real headache, forcing you into costly and complicated corrections. You might have to return contributions to your top earners (who won't be happy) or make extra contributions for your other employees to bring the plan back into balance.
The Safe Harbor Match: A Path To Simplicity
This is where the structure of your employer match can become your most powerful compliance tool. If you design your plan with a Safe Harbor match, you can automatically pass most of these annual testing headaches. For nonprofits, this offers a clean, predictable way to slash administrative work and compliance risk.
By choosing a Safe Harbor formula, you're building fairness directly into the plan's DNA. It simplifies everything on the backend and sends a clear message that you're committed to offering an equitable benefit to every single person on your team.
A very common Safe Harbor formula involves matching 100% of an employee's contributions on the first 3% of their pay, plus a 50% match on the next 2%. The key tradeoff? Any employer contributions made under a Safe Harbor plan must be 100% vested immediately. That money belongs to the employee from day one.
Going this route removes the annual stress and uncertainty of testing. It gives both your organization and your employees a predictable, stable benefit while ensuring you meet your fiduciary duties. For a deeper dive into plan rules, you can find more on ERISA compliance and what it means for your governance.
Offering a competitive match is a bigger deal than you might think. Not every employer does it. In fact, Bureau of Labor Statistics data shows that 49% of organizations offer no match at all, leaving nearly half of workers on their own. And of the 51% of plans that do have a match, only 10% provide 6% or more. As these 401(k) match statistics on UpCounsel.com show, this gives nonprofits a huge opportunity to stand out and attract the talent they need to drive their mission forward.
Communicating Your Retirement Benefits For Maximum Impact
A well-designed retirement plan is only half the battle. If your team doesn't understand it, they won't use it. Even the most generous employer match is worthless if your staff has no idea how to take advantage of it. Good communication turns your match from a line item in a budget report into a tangible, celebrated part of your culture.
The goal here is simple: cut through the financial jargon and show each person what’s in it for them. When an employee sees exactly how your match makes their savings grow faster, their entire perspective shifts. They’re far more likely to jump in, which is a win for their financial wellness and a boost for team morale.
Simplify The Message
Let's be honest—most people are intimidated by financial topics. Ditch the complex terminology and focus on what the benefit actually does for them. Simple, direct language always wins.
Think of it as translating a dry policy into a personal story. Instead of rattling off contribution percentages and vesting schedules, frame it as a partnership.
The most powerful message is often the simplest: "When you save for your future, we'll help you get there faster by adding our own money to your account."
This approach strips away the intimidation factor. It makes participation feel accessible and easy, no matter someone’s financial background.
Key Communication Touchpoints
A single mention during the annual benefits meeting isn't enough. To make the message stick, you have to weave it into the entire employee experience.
- During Recruitment: Don't hide your employer match 401k in the fine print. Showcase it as a core part of your total compensation package—it’s a powerful magnet for top talent.
- New Hire Onboarding: Make the retirement plan a star of the show. Walk new team members through enrollment and use clear, real-world examples to explain how the match works.
- Annual Benefits Enrollment: This is your annual reminder. Share anonymized success stories or visuals that show how a consistent contribution, supercharged by a match, can build real savings over time.
- Regular Check-ins: A quick note in a newsletter or a mention in an all-staff meeting can work wonders. A simple reminder that they might be leaving "free money" on the table is often all it takes to get someone to act.
Using Analogies To Explain The Match
To truly make the concept click, lean on simple analogies from everyday life. These comparisons can turn an abstract financial idea into something concrete and memorable.
For instance, you could frame it as a buy-one-get-one sale. "For every dollar you put into your retirement account, we'll put one in, too—up to a certain amount. You wouldn't walk past a BOGO deal at your favorite store, so don't miss out on this one for your future."
Another great one is a "savings amplifier." You can explain that their contribution is the initial sound, but the employer match is the amplifier that makes it much louder and more powerful. These little stories make the benefit feel real and drive home just how valuable it is.
Common Questions About Nonprofit Employer Matches
As your nonprofit's leaders and board members start thinking about retirement benefits, some big questions always come up. An employer match is a serious commitment, so getting clear answers is the only way to make a smart decision. This section tackles the most common questions we hear, helping you move forward with confidence.
Can We Change Our Match Formula Later?
Yes, you can—and many nonprofits do. It’s common to amend your plan to change the employer match. For example, if your organization has a great year with strong funding, you might decide to increase the match to stay competitive and reward your team. On the other hand, during leaner years, you might need to temporarily reduce or suspend it.
But you can’t just flip a switch. Any change requires a formal amendment to your plan document. You also have to give all your employees proper notice, usually 30 to 90 days in advance. The rules get much tighter for Safe Harbor plans, which often restrict your ability to lower or pause the match mid-year.
What Happens To Forfeited Funds?
When an employee leaves before they are fully vested, the unvested portion of your matching contributions is forfeited. These funds don’t go back into your nonprofit's general operating budget; they stay within the plan.
Your plan document will spell out exactly how you can use those forfeited funds. The most common options are:
- Reduce future employer contributions, which is a great way to help your budget.
- Pay for plan administration expenses, lowering the overall cost of running the plan.
- Reallocate the funds to the remaining plan participants.
Using forfeitures to offset your next round of contributions is a popular and effective strategy for managing the cost of an employer match 401k.
Are Employer Contributions Tax-Deductible?
This is a great question, and the answer works a bit differently for nonprofits. For-profit organizations get to deduct their employer contributions to lower their taxable income. Since most nonprofits are tax-exempt, you don't pay income tax in the first place.
So, the benefit isn't a tax deduction. Instead, it's a strategic tool for attracting and keeping the talented people who power your mission. For your employees, though, the tax advantages are huge. Your matching dollars, along with their own pre-tax savings, grow tax-deferred until they take the money out in retirement. That tax-deferred growth is a powerful part of their total compensation.
A common misconception is that a nonprofit doesn’t receive a “benefit” from matching since it’s not a tax write-off. The true benefit is mission-centric: it’s a commitment to the people who drive your cause forward, improving retention and organizational stability.
Navigating the details of retirement plans can feel complicated, which is why we've compiled even more answers. You might be interested in our other frequently asked questions for nonprofit leaders.
At NPDiva Consulting, we specialize in helping nonprofits design and manage retirement plans that align with their mission and budget. We provide clear, no-pressure guidance to help you care for your team while meeting your fiduciary responsibilities. Learn how NPDiva can support your organization.