

Joining a nonprofit board is a commitment born from passion, but it also comes with serious legal and ethical responsibilities. In simple terms, nonprofit board fiduciary duties are the fundamental obligations of care, loyalty, and obedience that every board member legally owes to the organization.
These duties aren’t just suggestions; they are the essential guardrails for good governance. They ensure that every decision protects the nonprofit’s mission, its assets, and the public’s trust.
The Three Pillars Of Nonprofit Board Governance
When you step into a board role, you become a steward of a community trust. Your decisions have a direct impact on the organization’s ability to fulfill its purpose. Understanding your fiduciary duties isn’t about memorizing legal jargon—it’s about embracing a framework for responsible, mission-focused leadership.
Rooted in both common law and state statutes, these obligations form the bedrock of good governance. Think of them as the three pillars holding up the entire structure of your nonprofit. They are mandatory, not optional, and they protect the organization, its mission, and you as a board member.
The Core Fiduciary Duties Explained
At their heart, these three duties ensure the board always acts in the nonprofit’s best interests. Each one addresses a different aspect of that core principle, and they work together to create a culture of integrity and accountability.
Here’s a breakdown of what they mean in practice:
- The Duty of Care: This is your duty to be present, prepared, and prudent. It means you must actively participate in meetings, review materials like financial statements before you vote, and ask clarifying questions until you understand the issues at hand. You can’t just show up; you have to be engaged.
- The Duty of Loyalty: This demands your undivided allegiance to the nonprofit. You must always put the organization’s interests ahead of any personal or professional gain. This involves transparently disclosing and managing any potential conflicts of interest, from business relationships to family connections.
- The Duty of Obedience: This is your obligation to keep the organization true to its purpose. You must ensure the nonprofit follows its own bylaws, stays faithful to its stated mission, and complies with all applicable laws and regulations. It’s about keeping the organization on its chartered course.
To help clarify these concepts, here is a summary of each duty with a practical example.
The Three Fiduciary Duties at a Glance
- Fiduciary Duty: Duty of Care
- Core Principle: Act with reasonable prudence and diligence.
- Nonprofit Board Example: Reading the financial reports and meeting agenda before the board meeting and asking informed questions.
- Fiduciary Duty: Duty of Loyalty
- Core Principle: Put the organization’s interests above your own.
- Nonprofit Board Example: Disclosing that your construction company is bidding on the nonprofit’s new building project and recusing yourself from the vote.
- Fiduciary Duty: Duty of Obedience
- Core Principle: Ensure faithfulness to the mission and applicable laws.
- Nonprofit Board Example: Intervening if the board considers using restricted grant funds for a purpose outside the grant’s stated goals.
These duties provide a clear, ethical compass for board leadership, guiding directors to make thoughtful decisions and prevent the misuse of charitable assets.
Failing to uphold these standards can expose both the nonprofit and its individual board members to significant risks, including legal liability, financial penalties, and lasting reputational damage. That’s why a firm grasp of what each duty requires is so critical. For a deeper dive into this topic, you can find more information about these essential fiduciary duties and their real-world applications.
Throughout this guide, we’ll explore each of these pillars in greater detail, offering practical steps to help you fulfill your responsibilities with confidence and protect the mission you’ve committed to serve.
Putting The Duty Of Care Into Practice
Of all the responsibilities on a nonprofit board member’s plate, the Duty of Care is arguably the most hands-on. It demands more than good intentions; it requires informed, diligent action. Think of it as the difference between hoping your roof won’t leak and actually inspecting it for loose shingles or hiring an expert to assess its condition.
This same principle applies directly to the boardroom. A passion for the mission is essential, but it can’t replace the hard work of due diligence. The stakes are just too high.
When an estimated 30% of nonprofits could close their doors within a decade—often due to lapses in basic oversight—it’s clear that the Duty of Care is a cornerstone of sustainable governance. For a deeper dive into the legal framework, you can explore these insights on the ultimate responsibilities of nonprofit directors.
Active Engagement And Inquiry
Satisfying this duty means more than just showing up. It means arriving prepared, having read the materials, and being ready to engage in meaningful conversation. It’s about active participation, not passive attendance.
The Duty of Care compels you to ask clarifying questions. If a financial report is confusing or a budget has a number that doesn’t add up, your job is to speak up and ask for an explanation until the issue is clear.
The Duty of Care isn’t about having all the answers. It’s about having the diligence to ask the right questions and the prudence to act on the information you get. Good faith alone isn’t enough; informed judgment is the standard.
While acting in “good faith” is part of the equation, it won’t shield a board member who makes a decision without first taking reasonable steps to get informed. This is where having a consistent and documented process—procedural prudence—becomes your best protection.
Key Actions For Fulfilling The Duty Of Care
So, how do you translate this legal duty into real-world action? It comes down to building a few key habits that create a foundation for responsible governance.
- Consistent Meeting Attendance: Be present at board and committee meetings. Your absence leaves a hole in the group’s collective oversight and deliberation.
- Thorough Preparation: Read your board packet—financials, program reports, previous minutes—before the meeting starts.
- Informed Questioning: Never be afraid to question assumptions or ask for more data. A culture of healthy inquiry makes the entire board stronger.
- Careful Deliberation: Take the time to discuss the pros and cons of a major decision. Thoughtfully weigh the risks and benefits before you cast your vote.
Following these steps consistently demonstrates that you are exercising the care that any ordinarily prudent person would in a similar situation.
Extending Care To Retirement Plan Oversight
This duty doesn’t stop at general finances; it extends directly to the oversight of the nonprofit’s retirement plan, whether it’s a 403(b), 401(k), or 457 plan. For most organizations, this is a major financial asset and a crucial employee benefit, making it a critical area of fiduciary focus.
Here, the key is procedural prudence. This means your job is to establish and follow a sound process for managing the plan.
This involves regularly monitoring your vendors, benchmarking plan fees to make sure they are reasonable, and documenting the decisions made by the board or retirement plan committee. A lapse in care here can open the organization up to serious legal and financial risk, which is why understanding this duty is so vital for anyone involved with nonprofit retirement plans.
Upholding The Duty Of Loyalty To Avoid Conflicts
If the Duty of Care is about how you make decisions, the Duty of Loyalty is all about why. This core fiduciary duty demands your complete and undivided allegiance to the nonprofit’s mission. It’s simple in theory but can be tricky in practice.
It means every decision you make must be in the best interest of the organization, not for your own personal, financial, or professional benefit. You have to put the nonprofit first, always.
Identifying And Managing Conflicts Of Interest
A conflict of interest pops up anytime a board member’s personal interests—or those of a family member or business associate—have the potential to influence their decisions for the nonprofit.
The key word is potential. A conflict isn’t automatically a breach of duty. The real problem arises when that conflict isn’t disclosed and managed with total transparency.
Common conflicts often look like this:
- Financial Interests: A board member owns a marketing firm that is bidding on a contract with the nonprofit.
- Family Connections: The board is asked to approve the hiring of the finance director’s son for a summer internship.
- Competing Loyalties: A director sits on the boards of two different food banks competing for the same major grant.
When personal ties start to blur the lines in the boardroom, you’re looking at a potential breach of loyalty. These situations can erode trust, drain assets, and undermine your mission. In fact, unchecked conflicts can contribute to the 30% nonprofit closure rate seen within 10 years.
The best defense is a strong, written conflict-of-interest policy that is reviewed annually and signed by every single board member. You can find more details on the legal foundation of these fiduciary responsibilities for nonprofit directors.
The Disclosure And Recusal Process
The existence of a conflict isn’t the real issue—it’s the failure to be transparent about it. Managing these situations effectively comes down to a clear, two-step process that should be written into your policy and followed religiously.
- Disclosure: The moment a potential conflict arises, the board member involved must fully disclose the nature of their interest to the entire board. This should be done in writing through an annual form and verbally during any relevant discussion.
- Recusal: After disclosing the conflict, the board member must then recuse themselves from the conversation and the vote on that matter. In most cases, this means physically leaving the room to avoid any appearance of influence.
This isn’t a punishment. The disclosure and recusal process is a vital safeguard. It protects the individual from accusations of self-dealing and protects the nonprofit from making a compromised decision, reinforcing a culture of integrity.
Loyalty In Retirement Plan Governance
The Duty of Loyalty is especially important when it comes to overseeing your nonprofit’s retirement plan.
When you’re choosing or reviewing plan vendors—like your recordkeeper or administrator—the decision must be based only on what’s best for the plan and its participants. Your employees’ financial futures are at stake.
Personal relationships can quickly create conflicts here. If a board member’s college roommate is a professional bidding for the plan’s business, that’s a clear conflict. Even with the best intentions, objectivity is nearly impossible.
This is why a formal, documented process for vendor selection is non-negotiable. Issuing a Request for Proposal (RFP) and evaluating every candidate against the same objective criteria proves that your loyalty lies with your employees, not with personal connections.
Staying True With The Duty Of Obedience
If the Duties of Care and Loyalty cover the how and why of your board service, the Duty of Obedience is all about the what. This duty is your promise to keep the nonprofit organization true to its original purpose. It’s a commitment to uphold the mission, follow the rules in your governing documents, and comply with every applicable law.
Think of it as honoring the pact your organization made with its donors, its community, and the government when it was first created. Every decision the board makes must directly support that foundational promise.
Preventing Mission Creep
One of the biggest temptations for a passionate board is “mission creep.” This is the slow, often well-intentioned, drift into activities that don’t quite fit the organization’s stated purpose. It happens when a tempting grant opportunity appears for a program that’s slightly off-mission, or when a great new idea gains momentum before anyone stops to check it against the charter.
The Duty of Obedience serves as your organizational anchor. It forces the board to pause and ask a critical question: “Does this new initiative directly support the mission outlined in our articles of incorporation?” If the answer is no, it’s the board’s job to steer the ship back on course, even if it means saying no to new funding or a popular idea.
The Duty of Obedience isn’t about being rigid; it’s about being purposeful. It protects your organization’s resources, reputation, and legal standing by ensuring that every effort contributes directly to the specific charitable purpose you exist to serve.
This duty means you need to be intimately familiar with the organization’s core documents.
- Articles of Incorporation: This is the legal document filed with the state that defines your nonprofit’s purpose. It is the ultimate North Star for your mission.
- Bylaws: These are the internal operating rules for your organization. The Duty of Obedience requires you to follow them for everything, from board voting procedures to officer elections.
- Mission Statement: While sometimes more aspirational, your mission statement is a public declaration of your purpose and a vital touchstone for every strategic conversation.
The Foundation Of Legal Compliance
Beyond just staying on-mission, the Duty of Obedience has a critical legal side. The board is ultimately responsible for making sure the organization follows all local, state, and federal laws. This is a non-negotiable part of nonprofit board fiduciary duties.
This legal framework covers a huge range of obligations:
- Maintaining Tax-Exempt Status: This means following all IRS rules for 501(c)(3) organizations, including filing the annual Form 990 on time and avoiding activities that could create too much unrelated business income or provide a private benefit to an insider.
- Following Fundraising Regulations: Nonprofits must comply with all charitable solicitation laws in every state where they raise money.
- Adhering to Employment Laws: This covers everything from fair hiring practices and safe working conditions to proper payment of wages.
- Complying with Retirement Plan Rules: For nonprofits offering a 403(b) or another retirement plan, the Duty of Obedience means following the specific rules laid out by laws like the Employee Retirement Income Security Act (ERISA).
That last point is incredibly important. When it comes to retirement plans, obedience means making sure the plan document is followed to the letter and all regulatory requirements are met. You can explore our resources to learn more about how to choose the right retirement plan that aligns with both your organizational goals and your fiduciary responsibilities.
By upholding the Duty of Obedience, the board builds a strong foundation of legal and ethical integrity. This protects the nonprofit from penalties, sanctions, and the potential loss of its precious tax-exempt status.
When your nonprofit offers a retirement plan like a 403(b), the board or a designated committee suddenly wears a new hat: a plan fiduciary under the Employee Retirement Income Security Act (ERISA). This isn’t just a change in title. This federal law raises the stakes, turning your general nonprofit board fiduciary duties into specific, legally enforceable responsibilities.
Suddenly, your duty isn’t just about general financial oversight for the organization. You’re now legally required to manage the retirement plan solely for the benefit of your employees and their beneficiaries. It’s a serious responsibility that demands a focused, documented process.
It’s All About Procedural Prudence
When it comes to retirement plan oversight, the most important concept to grasp is procedural prudence. This is a fancy way of saying your legal protection doesn’t come from picking the “perfect” plan that outperforms everything else. It comes from following and documenting a sound, consistent process.
Think of it this way: The Department of Labor, which enforces ERISA, cares less about which vendor you picked and far more about how you picked them.
Your job is to prove you acted with the care and diligence of a prudent expert. That means creating a paper trail showing you asked the right questions, compared your options, and made informed decisions.
A strong process is your best defense as a fiduciary. When ERISA is involved, documented diligence is infinitely more valuable than impressive plan returns. The focus is on making prudent choices, not guaranteeing outcomes.
Building Your Governance Framework
To manage these duties well, you need a formal governance structure. Just talking about the retirement plan once a year at a board meeting simply won’t cut it. The best practice is to form a dedicated committee to ensure the plan gets the focused attention it requires.
Here are the essential steps to build that structure:
- Form a Retirement Plan Committee: Create a dedicated group responsible for plan oversight. This committee can dig into the details in a way the full board never could.
- Draft a Committee Charter: This is your committee’s rulebook. It’s a formal document that outlines the group’s purpose, roles, and responsibilities, defining exactly who is in charge of what.
- Create a Plan Governance Document: A governance document is the playbook for your plan. It lays out the criteria for selecting, monitoring, and evaluating your service providers. It’s all about process, not picking specific options.
- Schedule Regular Meetings: The committee should meet at least annually—but quarterly is even better—to review plan administration, check on vendor performance, and confirm fees are reasonable.
Taking these steps is a clear signal that you’re embracing your Duty of Care. It establishes a system for active, informed oversight instead of just passive approval. To see what can go wrong without this structure, you can read about the top retirement plan mistakes nonprofits make and how to fix them.
The diagram below shows how the Duty of Obedience fits into this puzzle, ensuring every action you take lines up with your mission, bylaws, and the law.
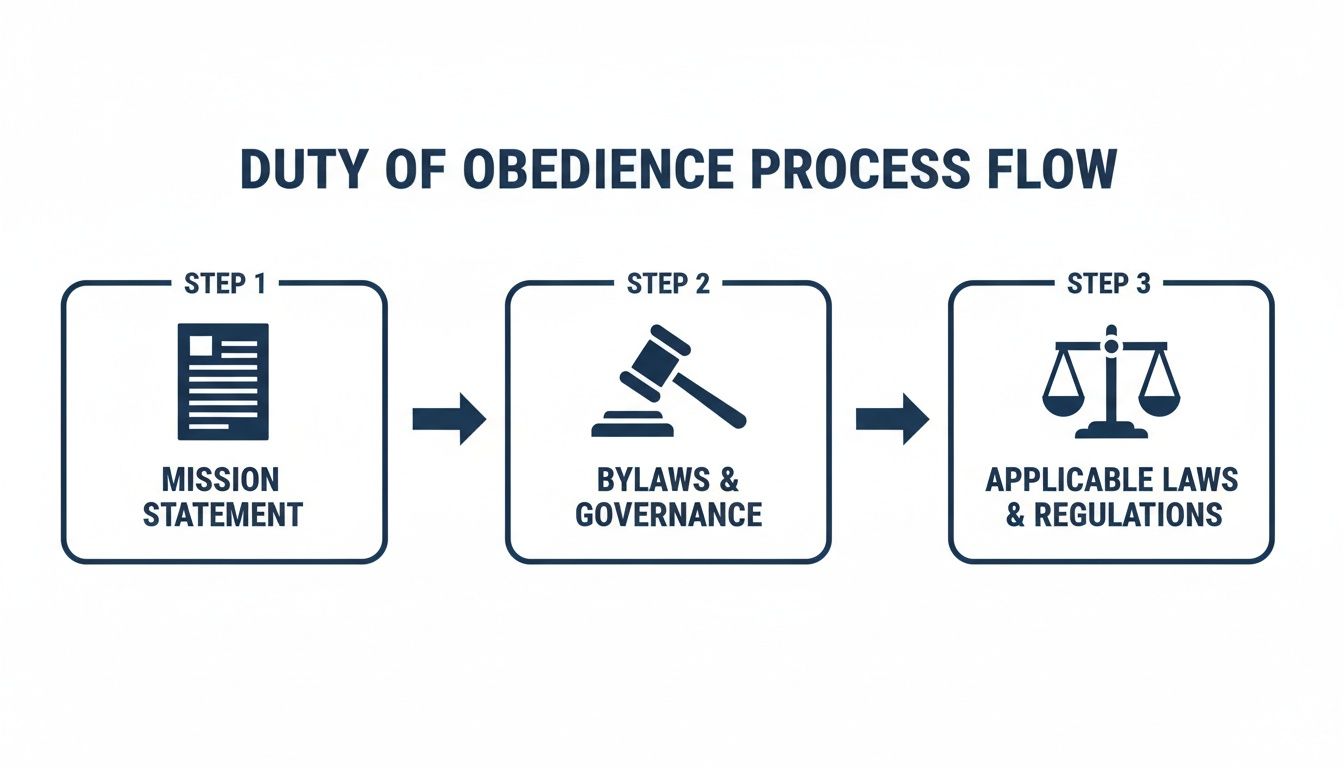
As you can see, obedience starts with your mission and flows through all legal requirements, including the strict rules set by ERISA.
Overseeing Vendors and Keeping Fees Reasonable
A huge part of your fiduciary role is keeping an eye on the vendors who help run your plan, like recordkeepers and third-party administrators. Your Duty of Loyalty requires you to select and monitor these partners through an objective process, free from any conflicts of interest.
This means you have to make sure all fees paid from the plan are reasonable for the services being provided. High or hidden fees can quietly drain your employees’ retirement savings over the years, and fiduciaries who fail to monitor them are often found in breach of their duties.
Here’s how your committee can fulfill this duty:
- Benchmark Your Fees Regularly: At least every few years, compare your plan’s fees to other nonprofit plans of a similar size. This is the only way to know if what you’re paying is fair and competitive.
- Conduct a Formal RFP: Don’t be afraid to put your plan out to bid. Issuing a Request for Proposal (RFP) forces vendors to compete for your business and creates a fantastic paper trail of your due diligence.
- Document Your Decisions: Keep detailed minutes from every committee meeting. If you decide to stick with a vendor who charges a bit more, your minutes should clearly explain why—perhaps they offer superior service or technology that justifies the cost.
Retirement Plan Fiduciary Governance Checklist
To bring it all together, here is a practical checklist your nonprofit’s board or retirement plan committee can use to stay on top of your duties. Think of this as your roadmap to sound governance.
Governance Task: Establish a Committee
- Key Action: Form a dedicated retirement plan committee with a clear charter.
- Associated Fiduciary Duty: Duty of Care
Governance Task: Document Processes
- Key Action: Create and maintain a plan governance document.
- Associated Fiduciary Duty: Duty of Care
Governance Task: Hold Regular Meetings
- Key Action: Meet at least annually (quarterly is better) to review the plan.
- Associated Fiduciary Duty: Duty of Care
Governance Task: Benchmark Fees
- Key Action: Compare all plan fees against industry averages every 2-3 years.
- Associated Fiduciary Duty: Duty of Loyalty
Governance Task: Review Vendors
- Key Action: Conduct periodic RFPs to ensure vendor services and costs are competitive.
- Associated Fiduciary Duty: Duty of Loyalty
Governance Task: Keep Detailed Minutes
- Key Action: Document all discussions, decisions, and the rationale behind them.
- Associated Fiduciary Duty: Duty of Care
Governance Task: Ensure Compliance
- Key Action: Confirm the plan follows its own documents and all applicable laws (ERISA).
- Associated Fiduciary Duty: Duty of Obedience
Using a checklist like this helps turn abstract duties into concrete actions. It ensures nothing falls through the cracks and creates the documented, prudent process that is the cornerstone of fulfilling your nonprofit board fiduciary duties. Following these steps protects your organization, your board, and most importantly, the financial future of the employees you’re there to serve.
Building Your Fiduciary Governance Toolkit
It’s one thing to understand the theory behind your fiduciary duties. It’s another thing entirely to put it into practice day-to-day. The final step in creating strong governance is building the tools and processes to uphold those duties consistently, turning good intentions into documented habits that protect your organization and its leaders.
This isn’t about adding bureaucracy. It’s about creating a practical toolkit that minimizes personal and organizational liability, builds unshakable trust with donors, and frees your board to focus on what matters most—delivering on your nonprofit’s mission.
Your Best Defense: Detailed Documentation
In the world of nonprofit board fiduciary duties, if it isn’t written down, it didn’t happen. Your single most important defense is a set of detailed, accurate board meeting minutes. They are the official record proving your board is exercising its Duty of Care through diligent oversight and thoughtful deliberation.
Great minutes do more than just record votes. They capture the story behind the decision:
- The key points of major discussions.
- Questions that were asked and the answers provided.
- The alternatives considered before a decision was made.
- The rationale behind the final vote.
This level of detail creates a clear paper trail, demonstrating that the board engaged in a prudent, informed decision-making process.
The Fiduciary Action Log
To take documentation a step further, many boards create a Fiduciary Action Log. This is a simple but powerful tool—often just a running document or spreadsheet—used to track major governance decisions throughout the year. Think of it as a high-level summary of your most critical actions.
For each significant decision, like approving a new budget or selecting a retirement plan vendor, the log should briefly note:
- The Decision: What was decided.
- The Date: When the decision was made.
- The Process: What steps were taken (e.g., reviewed three proposals, consulted an expert).
- The Rationale: Why this choice was made in the best interest of the nonprofit.
This log provides an at-a-glance view of your fiduciary diligence, which is invaluable during an audit or if a past decision ever comes into question.
Creating a Dedicated Governance Committee
While the full board holds ultimate responsibility, forming a dedicated governance or fiduciary oversight committee is a clear best practice. This smaller group can give critical governance tasks the focused attention they deserve, which is often difficult to achieve in a full board meeting.
A governance committee acts as the engine room for your board’s fiduciary responsibilities. It ensures policies are current, board members are trained, and oversight processes are consistently followed, strengthening the entire organization’s integrity.
This committee is typically charged with overseeing bylaws, managing the board member nomination process, running board assessments, and ensuring conflict-of-interest policies are followed.
The Non-Negotiable Role of Insurance
No matter how diligent your board is, mistakes can still happen. That’s why Directors and Officers (D&O) liability insurance is absolutely non-negotiable. This insurance protects board members from personal liability in the event of a lawsuit alleging a breach of fiduciary duty.
Having a D&O policy is, in itself, an act of fiduciary prudence. It protects the personal assets of the volunteers who dedicate their time to your mission, which in turn makes it easier to recruit and retain high-quality board members.
This proactive risk management also extends to your employees’ futures. Ensuring your retirement plan is well-managed is crucial, and you can learn more about how to reduce retirement plan administration costs without compromising value. Strong governance is a strategic asset that protects your ability to operate effectively for years to come.
Frequently Asked Questions About Nonprofit Fiduciary Duties
Even for the most dedicated nonprofit leaders, the subject of fiduciary duties can bring up a lot of practical “what-if” questions. Getting clear, straightforward answers is the best way to build confidence and ensure your board is operating from a position of strength.
Here are a few of the most common questions we hear from nonprofit boards.
What Happens If A Board Member Breaches A Fiduciary Duty?
A breach of fiduciary duty is serious and can have lasting consequences, both for the individual and the organization. The board member could be held personally liable for any financial losses the nonprofit suffers because of their actions.
Beyond the financial risk, a breach can trigger legal action and cause severe damage to the organization’s reputation, which can quickly erode donor trust.
This is exactly why having a strong Directors and Officers (D&O) insurance policy is so important. It acts as a financial safety net for board members who act in good faith. But remember, insurance is there for when things go wrong—it’s no substitute for diligent oversight.
Can A Board Member Be Liable For A Good Faith Decision That Fails?
Typically, no. This is where a legal principle called the business judgment rule provides protection. Courts understand that not every decision will lead to a perfect outcome, and they generally shield board members from liability for honest mistakes.
The key to being protected by the business judgment rule is proving you followed a sound process. The board must show it exercised its Duty of Care by acting on an informed basis, with diligence, and with an honest belief that the decision was in the nonprofit’s best interest. The focus is on a prudent process, not a flawless result.
The best way to demonstrate a prudent process is to document your discussions, research, and final decisions in your board meeting minutes.
How Often Should Our Board Review Fiduciary Responsibilities?
It’s a best practice to review fiduciary duties annually. This shouldn’t be a stuffy, formal exercise. Think of it as a cornerstone of your board culture.
This review should be a standard part of onboarding for new members and serve as an annual refresher for the entire board. A quick, focused discussion on the three core duties, your conflict of interest policy, and other key governance practices keeps these obligations top-of-mind and reinforces your commitment to good governance.
Navigating the complexities of nonprofit board fiduciary duties, especially as they apply to retirement plans, requires a dedicated partner. Expert guidance can help your organization meet its responsibilities with confidence. Learn more at https://npdiva.com.